Commercial investment
8% or 12% Yield? How to Compare Two Commercial Property Investments
Compare commercial investments beyond the headline yield: tenant strength, lease breaks, costs and a worked vacancy scenario for two hypothetical properties.
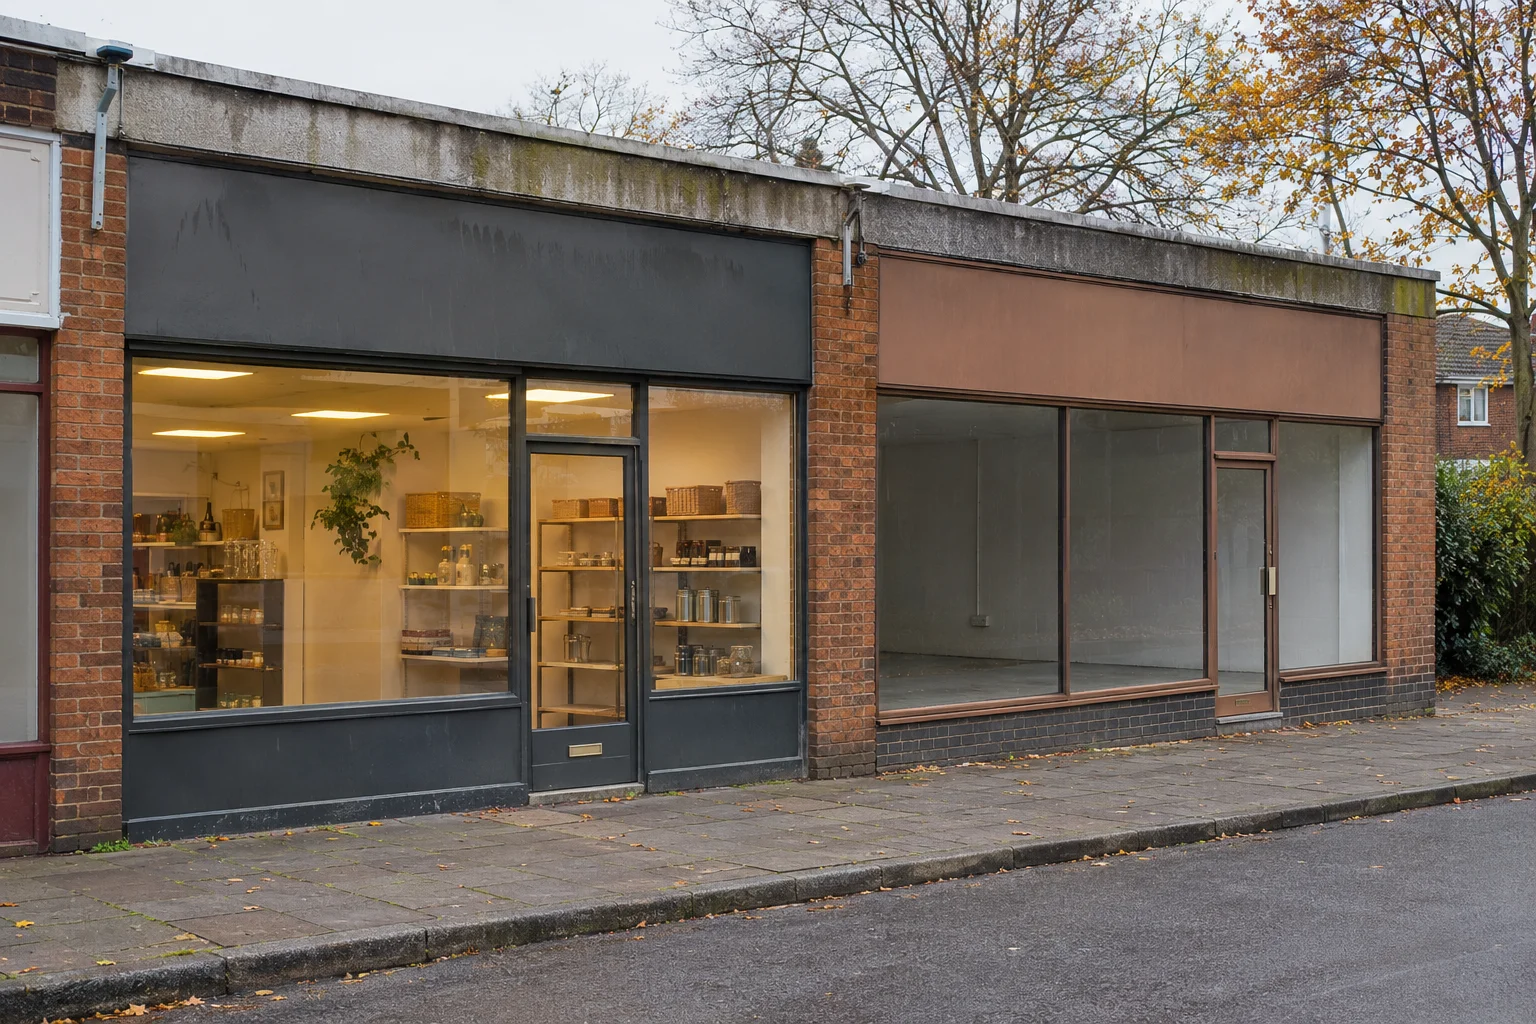
An extra four percentage points of yield looks rather appealing. Unfortunately, the roof, the tenant and the break clause have not yet introduced themselves.
An investment advertised at 12% is not automatically better than one at 8%. The useful question is what you are buying for that price: sustainable rental income, a particular lease, a tenant's ability to pay and a building you might eventually need to let again. Compare those things alongside the money required to buy and hold it.
This guide sets out a practical comparison for smaller commercial investments, including shops, workshops and industrial units. All figures are hypothetical illustrations, not current market averages, available deals or promises of returns. We begin without borrowing so that the property comparison is visible before finance complicates the picture.
First, make sure both percentages mean the same thing
A simple gross purchase yield is annual rent divided by the purchase price, multiplied by 100. If rent is £30,000 and the price is £375,000, the result is 8%. At a £250,000 price, the same rent produces 12%. The cheaper property has not created another pound of annual rent; you are paying less for the stated income.
That distinction matters when comparing advertisements. Ask whether the quoted rent is currently payable, actually being collected or merely an estimate for a future letting. Check whether a rent free period, stepped rent or landlord contribution changes the first year's receipts. An annualised headline can hide an unusually thin first twelve months.
Also establish the denominator. A calculation using the asking price excludes acquisition costs. A professional yield quotation may use different income and cost conventions. Ask the agent to explain its basis rather than assuming that every percentage on your shortlist was calculated identically.
For this article, gross yield uses the price alone. Our separate operating income return uses rent less assumed landlord operating costs, divided by total initial capital including acquisition and immediate works. Neither figure deducts finance or tax. Labelling the calculation makes comparison more useful than arguing about which label sounds most impressive.
Two properties, one rent, different questions
Consider two hypothetical buildings, each with £30,000 annual contractual rent. Property A costs £375,000 and shows an 8% gross yield. Property B costs £250,000 and shows 12%. Assume both collect the stated rent for a full year in our starting scenario. This is a deliberately controlled comparison, not a claim that equivalent buildings normally sell at these prices.
For A, allow £20,000 for acquisition costs and immediate works, giving £395,000 total initial capital. Assume £3,000 a year of landlord operating costs. That leaves £27,000 before finance and tax, or approximately 6.84% of the initial capital. These allowances would need actual quotes and professional input for a real purchase.
For B, allow £35,000 for acquisition costs and immediate works, giving £285,000 total initial capital. Assume annual landlord operating costs of £6,000. That leaves £24,000 before finance and tax, or approximately 8.42%. B still offers the higher illustrated operating return, but the gap has narrowed and its annual cash surplus is lower.
The assumptions are intentionally different because buildings rarely present identical bills. Investigate survey findings, management requirements and unrecovered expenses. Replace both allowances with evidence; do not treat our numbers as standard fees or maintenance budgets. Keep an additional cash reserve visible, even though money held in reserve is not itself an expense.
Read the tenant's name, not just the shop sign
A recognisable brand above the door can be reassuring, but establish which legal entity actually owes the rent. It could be a substantial trading company, a local franchise operator or a smaller subsidiary. Do not assume that a parent company stands behind the lease unless the documents provide an enforceable obligation.
Request the tenancy schedule, available financial information and evidence of rent payments. Discuss the depth and limitations of the financial review with your advisers. Filed accounts may be historic, and a clean payment record cannot guarantee future performance. It can still help you distinguish a functioning income stream from an optimistic description.
Ask practical questions too. How dependent is the occupier on this location? Does the layout suit its business? Is the rent affordable within the trading model? A tenant that needs the building but cannot sustain the rent presents a different proposition from one paying a sensible rent for useful premises.
For our comparison, imagine A has a financially stronger tenant and B a smaller business with less evidence available. That does not make B unacceptable. It means the higher return needs to be assessed against greater uncertainty and your ability to carry the property if income stops.
A ten-year lease may contain a two-year decision
Remaining lease length is useful, but the earliest effective break can be more relevant to your planning. Ask your solicitor to explain who can exercise each break, its date, notice requirements and conditions. A long contractual term does not necessarily mean the tenant must stay for all of it.
In our hypothetical comparison, suppose A has six years before the next tenant break, while B has eighteen months. That is a significant difference even if both marketing descriptions mention long leases. Your review should include side letters, variations and any other agreements affecting occupation or payment.
Check rent review provisions and the evidence required to support a change. An owner cannot simply replace an agreed rent with the number needed to achieve a target yield. Equally, an apparently attractive passing rent might exceed what a replacement occupier would pay.
This is where tenant, lease and property become one investment. A dependable occupier on a sustainable rent with useful lease protection may justify a different price from a weaker income stream. RICS guidance on comparable evidence identifies tenant covenant strength and lease terms among relevant investment comparisons. That supports investigating the differences, rather than assuming yield alone describes value.
What would happen if the tenant left?
Imagine viewing the building without the current signage, furniture or business activity. Who would want it next? For an industrial unit, consider loading, power, access and layout. For a shop, consider frontage, servicing, nearby occupiers and plausible uses. A building can be well occupied today yet awkward to relet.
Ask local commercial agents for relevant completed lettings, incentives and realistic marketing periods. Distinguish an asking rent from an achieved agreement. Check how closely the evidence matches the unit's size, condition and lease terms. A larger modern building across town may tell you very little about an older, smaller property.
If geography is central to your decision, our East Midlands industrial location guide explains how to compare practical occupier needs. Do not add a location premium simply because a brochure mentions a motorway. The final approach, local competition and available workforce still deserve attention.
Write down the reletting work rather than putting “find new tenant” into a spreadsheet cell. There may be clearance, repairs, marketing, professional fees and incentives before income restarts. Identify which costs are supported by quotes, which are provisional and which require investigation.
Put the 12% property through an uncomfortable year
Return to B, with £30,000 expected rent and £6,000 assumed annual landlord operating costs. Suppose the tenant leaves and six months pass without rent. Receipts for that year fall to £15,000. Keep the £6,000 baseline allowance and add an illustrative £8,000 for incremental vacancy, reletting and repair costs.
That leaves just £1,000 before finance and tax: £15,000 less £6,000 less £8,000. On £285,000 initial capital, the illustrative return for that year is about 0.35%. Ensure the extra allowance contains only costs not already counted. Actual vacant-property liabilities and reliefs need checking for the property concerned.
Now stress A too. A lower yield does not protect against tenant failure, building defects or changing demand. Run the same vacancy duration, then a separate property-specific scenario reflecting its lease and condition. The point is to discover the amount and duration of cash support each investment might require.
Compare a sequence of years rather than one perfect year against one disastrous year. A genuine opportunity can withstand a difficult period and still meet your objectives. A weaker purchase may only look attractive because the model assumes continuous occupation, full collection and no significant expenditure.
Repairs belong in the comparison before the offer
A full repairing and insuring description does not replace reading the lease and commissioning an appropriate survey. Establish the actual obligations, any schedule of condition, exclusions and recovery arrangements. Your adviser should assess the documents alongside the state of the building, including material work expected during ownership.
The government's guide to business tenant responsibilities explains that repair and maintenance responsibilities depend on the lease. Costs that are theoretically recoverable still require attention to the tenant's ability to pay. During a vacancy, there may be nobody from whom to recover them.
For each property, keep a short schedule of immediate expenditure, foreseeable works and unresolved risks. Identify who is contractually responsible and what evidence supports recovery. This prevents a cheap building with deferred expenditure being compared unfairly with a more expensive building whose condition has already been addressed.
Keep valuation yield separate from your spending-money return
A simplified income capitalisation illustration divides annual net income by a selected yield. At £30,000 net income, 8% indicates £375,000 and 12% indicates £250,000. Here the £30,000 is explicitly assumed net income, unlike the gross contractual rent in our opening comparison. The distinction is essential.
That arithmetic does not tell you which yield a valuer should adopt. RICS explains the investment valuation method in terms of assessing market rent and a market-based yield. Appropriate evidence, lease structure and property characteristics determine the assessment; choosing 8% because it produces a nicer valuation is not analysis.
Our existing commercial cash flow and refinancing guide covers rent increases, borrowing and potential capital release. Use that as the next stage once the property comparison is sound. Borrowing changes your cash exposure and ongoing commitments, so obtain advice on actual lending terms rather than applying one assumed loan to both buildings.
Three questions before choosing
Is a 12% commercial yield a warning sign?
It is a reason to investigate, not an automatic rejection. Establish why the price is lower relative to rent. The explanation could include location, lease timing, condition, tenant uncertainty or a genuine purchasing opportunity. Treat the advertised percentage as the beginning of the enquiry, not its conclusion.
Should I always choose the stronger tenant?
No single factor should decide the purchase. A strong tenant cannot correct an excessive price or every property defect. Compare the whole investment against your objectives, cash reserves and management capacity. Decide which risks you understand and can afford before negotiating, rather than after becoming attached to the property.
What should I ask the agent for first?
Request the lease and variations, tenancy schedule, rent payment information, available outgoings and service charge details, property particulars and relevant reports. Record missing information explicitly. Then agree the necessary legal, survey, valuation and financial checks with qualified advisers before committing.
Turn the comparison into a useful search brief
Tell PropSelect the income you are seeking, available capital, purchase budget, preferred locations, funding position and appetite for vacant or older buildings. Explain how much involvement you want and what cash buffer you need to retain. Those details help define acceptable compromises more clearly than a minimum yield alone.
We source commercial property below £2 million across the East Midlands, Peterborough and the Golden Triangle. An engagement fee and percentage purchase fee are agreed in writing before instruction. Financial, tax, legal and survey advice comes from appropriately qualified professionals. Figures here illustrate a decision process; income and capital values can fall.
Send Ashley your commercial investment brief. We can start with what the investment needs to do, then ask why a particular yield is being offered.
General information checked on 16 November 2026. Examples are hypothetical and exclude finance and tax unless expressly stated. They are not valuations, lending offers or forecasts.